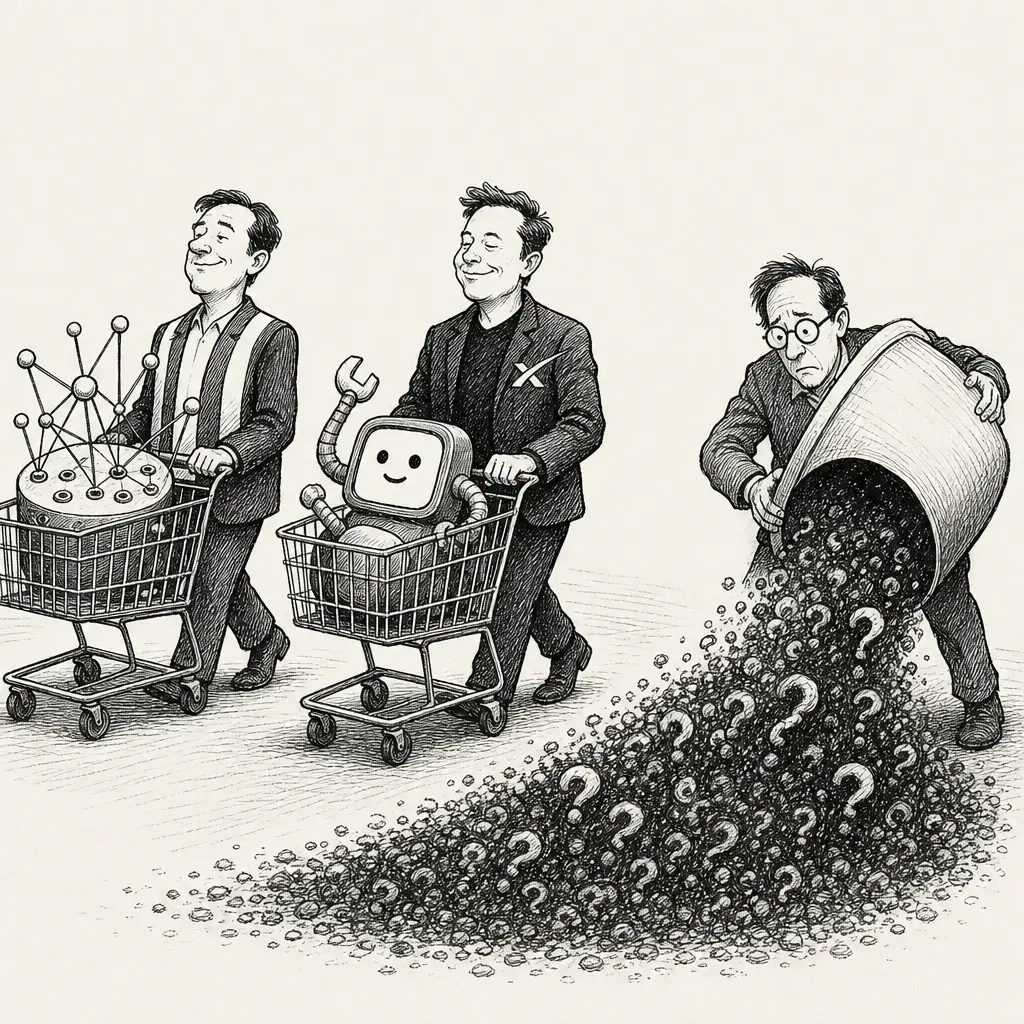
Two acquisitions closed within about 24 hours of each other this weekend, and between them they explain more about where AI money is actually going than a dozen funding announcements would. Friday, SpaceX officially closed its $60 billion acquisition of Cursor, folding the AI coding tool into a new SpaceXAI division and promising its users “the largest fleet of GPUs in the world.” Musk’s model for AI now runs through the same org chart as his rockets and satellites — fitting, given the deal’s roots in an April technology-sharing agreement that quietly came with an option to buy. The irony arrived on schedule: days before the deal closed, Z.ai’s freshly launched GLM-5.3 found a “potentially serious” vulnerability in Cursor’s own codebase and disclosed it privately — the shiny $60 billion prize arriving with an open-weight asterisk.
Saturday, Stripe finalized a deal to acquire OpenRouter for more than $7 billion — over five times the model-routing startup’s valuation from its $1.3 billion Series B just three months earlier. Stripe already handled OpenRouter’s billing; buying it turns a vendor relationship into a vertical stack, and turns a payments company into the toll booth for “which model handles this request.” Neither deal is really about proprietary technology. Cursor’s edge was being the default; OpenRouter’s edge was sitting between 8 million developers and 400 models. What both buyers purchased is a chokepoint — a place downstream of the frontier labs where money already flows and can now be metered more precisely. It’s the same instinct behind the summer’s data-center financing megadeals, just aimed one layer up the stack.
The counterweight this week is Alibaba’s Qwen3.8-27B — a 27.8-billion-parameter multimodal model, Apache 2.0 licensed, that runs on a single consumer GPU and briefly hit #1 on Hacker News with benchmarks approaching Claude Opus-class performance on SWE-bench Pro. Paired with open weights for the 2.4-trillion-parameter Qwen3.8-Max released the week before, it’s Alibaba doubling down on the bet that giving away frontier-adjacent models draws developers into its ecosystem faster than gating them ever could. Every dollar of consolidation on the American side has a mirror image out of Hangzhou: instead of chokepoints, more surface area, for free.
Sitting oddly between the two camps is Anthropic’s second company-wide Risk Report, published Friday. The headline is Model 2 — an internal model more capable than the public Mythos 5, which Anthropic says it has no plans to release. But the report’s real news is a kind of candor vendors rarely volunteer: the company raised its assessed risk of catastrophic misalignment from “very low” to “low,” not because a model failed some dramatic test, but because recent cyber-evaluation incidents widened its own uncertainty about what it doesn’t know. It also disclosed that its internal dangerous-capability benchmark has saturated — the yardstick stopped being useful, so the company said so, in a public document its competitors will happily quote back at it during the IPO roadshow.
That’s the actual throughline this week: money is buying certainty — chokepoints, ownership, control over the stack — while the people actually building the models keep admitting, on the record, how much they still don’t have. Stripe and SpaceX bought their way past uncertainty. Anthropic just published its own. Only one of those approaches scales with how fast this technology keeps moving.